The healthcare sector entered 2026 hoping for stability after several years of disruption tied to the pandemic, labor shortages and inflation. Early bankruptcy data now suggests financial pressure across the industry is intensifying again.
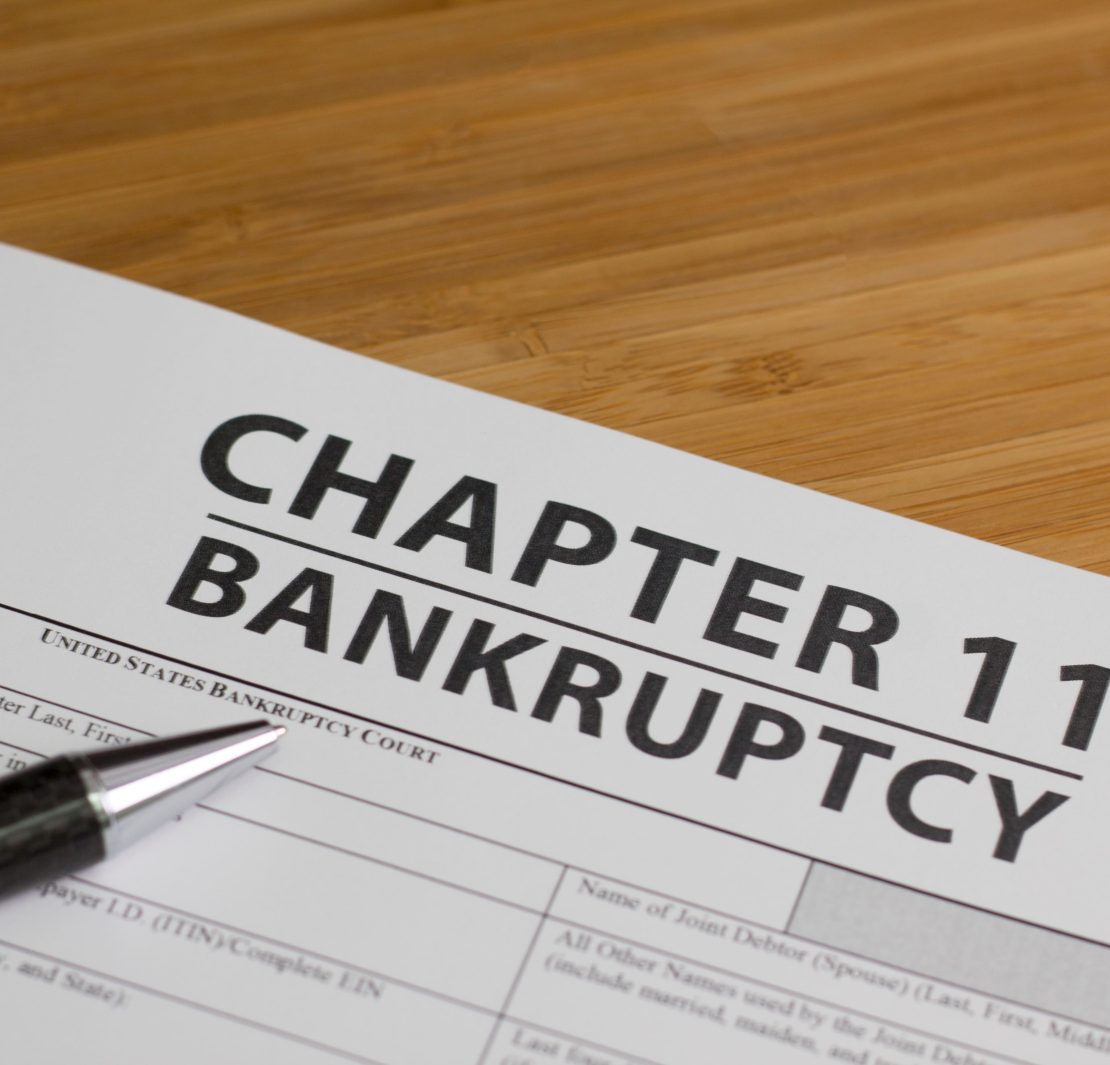
Twelve healthcare companies with liabilities exceeding $10 million filed for Chapter 11 protection during the first quarter of 2026, according to restructuring data cited by Yahoo Finance. The figure marked a 33% increase from the previous quarter and points to a sector still struggling with structural cost pressures, reimbursement disputes and uneven patient demand.
The increase does not yet match the crisis levels seen in 2023, when healthcare bankruptcies surged to 79 filings, though the trend is drawing renewed scrutiny from lenders, operators and policymakers. Analysts estimate the sector could finish 2026 with roughly 48 sizable healthcare bankruptcies, slightly above 2025 totals.
For healthcare executives, the issue is no longer whether financial stress exists. The question is which organizations remain equipped to absorb it.
Healthcare bankruptcies are climbing after a brief period of relief
The healthcare industry spent much of 2025 in recovery mode. Inflation cooled modestly, labor availability improved in certain markets and hospitals regained some elective procedure volume lost during earlier disruptions.
That recovery now appears uneven.
Senior care operators and physician practices accounted for most large healthcare bankruptcy filings during the first quarter. Both segments continue facing difficult operating conditions. Labor-intensive care models, thin reimbursement margins and dependence on aging facilities have created financial structures vulnerable to shifts in demand or payer behavior.
Mid-market healthcare organizations appear particularly exposed. Roughly two-thirds of first-quarter bankruptcy filings involved companies carrying between $10 million and $50 million in liabilities. These firms often lack the scale advantages available to large health systems while carrying debt burdens smaller operators may avoid.
The strain is visible across several healthcare categories, though not evenly distributed.
Hospitals continue facing pressure from staffing expenses and payer negotiations, though many large systems retain stronger balance sheets than physician groups or long-term care operators. Physician practices, particularly those backed by private equity, are encountering refinancing challenges as interest rates remain elevated. Senior care operators continue struggling with occupancy volatility, Medicaid dependence and rising insurance costs.
Healthcare has also become a growing concern for investors and ratings agencies. S&P Global recently identified healthcare as the highest-risk major US sector based on default probability and investor sentiment indicators.
That designation reflects a growing recognition that healthcare’s financial problems are no longer temporary aftereffects of the pandemic. Many have become embedded operational realities.
Rising costs and reimbursement pressure are squeezing margins
The healthcare sector’s financial strain comes from a collision between cost inflation and constrained reimbursement growth.
Labor remains one of the largest problems. Wage levels for nurses, technicians and specialized support staff remain significantly higher than pre-pandemic benchmarks. Many providers continue relying on contract labor in areas where recruitment remains difficult, even as patient reimbursement rates fail to keep pace with staffing expenses.
Providers are also reporting mounting frustration with Medicare Advantage reimbursement disputes and claim denials. Delayed payments and more aggressive utilization reviews have placed additional strain on cash flow, particularly for smaller physician groups and outpatient operators with limited financial reserves.
Policy uncertainty is adding another layer of risk.
The expiration of enhanced Affordable Care Act subsidies has raised concerns about insurance affordability for lower-income patients. Medicaid funding pressures in several states are increasing anxiety among providers serving large government-insured populations.
Borrowing conditions have compounded the challenge. Many healthcare firms financed expansion efforts or acquisitions during periods of historically low interest rates. Refinancing that debt in the current rate environment has become significantly more expensive.
This dynamic is especially problematic for organizations with weak margins or inconsistent revenue growth. Restructuring advisers increasingly describe healthcare firms as operationally viable businesses trapped by unsustainable capital structures.
Supply costs remain elevated as well. Pharmaceutical expenses, medical equipment pricing and insurance premiums continue weighing on provider budgets despite broader signs of moderating inflation across the US economy.
The result is a sector operating with limited flexibility at a time when financial resilience has become increasingly important.
Consolidation and restructuring are becoming survival strategies
Many healthcare leaders now see consolidation less as a growth strategy and more as a defensive necessity.
Hospital systems continue pursuing acquisitions of physician groups, outpatient centers and specialty operators in efforts to stabilize referral networks and spread administrative costs across larger organizations. Distressed assets are also creating acquisition opportunities for private equity firms and larger strategic buyers willing to absorb operational risk.
The industry is accelerating its shift toward outpatient and lower-cost care models. Health systems are investing more heavily in ambulatory surgery centers, home-based care and digital care delivery platforms that require lower fixed infrastructure costs than traditional inpatient facilities.
Operational restructuring has become equally important.
Providers are increasingly focused on revenue cycle management, staffing productivity and technology adoption aimed at reducing administrative overhead. Artificial intelligence tools are beginning to play a larger role in scheduling, billing workflows and claims management as organizations search for efficiency gains without reducing frontline care delivery.
Restructuring alone may not resolve deeper structural weaknesses.
Organizations heavily dependent on government reimbursement programs remain exposed to political and regulatory changes outside their control. Smaller regional operators also continue facing competitive pressure from larger systems with stronger negotiating leverage and greater access to capital markets.
The remainder of 2026 will likely determine whether the current rise in healthcare bankruptcies represents a manageable correction or the beginning of a more sustained period of financial instability.
For now, healthcare leaders are watching the same indicators closely: reimbursement trends, labor availability, interest rates and patient demand patterns. The organizations that adapt fastest to those pressures may define the next phase of the industry’s consolidation cycle.
Source